
First in line. Paid from production.

- $800,000
- Investment amount
- 36 months
- From the first investment in a class to its targeted repayment
- 2.25%
- Estimated annual distribution, $18,000 a year, subject to available cash flow
- 35%
- of all distributed profits to EB-5 investors, after all EB-5 investor capital is repaid
Investor capital is repaid from oil and gas production cash flow, not from a future refinance or commercial real estate sale as with many EB-5 offerings. For the first three years, production revenue after the fund’s dividend is reinvested in drilling additional wells. Repayment of a class is targeted for 36 months after the first investor in that class invests, and earlier classes are repaid before later ones. No profits are distributed to the managing partner or the operators until every investor class has had its capital returned.
The operating company pays the NCE a 9% annual dividend. After NCE operating costs, the remainder is split evenly between the managing partner and the EB-5 investors — the investors’ half is currently estimated at about 2.25% a year. An investor’s annual distribution continues after their own capital is returned, until all classes have been repaid. EB-5 investors then receive 35% of all distributed profits from ongoing production.
Repayment is a target, not a guarantee. The EB-5 required two-year capital sustainment period runs concurrently within this timeline.
Investors who file earlier are placed in earlier classes, and earlier classes are repaid first.

How your investment economics work
The investment is designed around three stages: annual distributions while investor capital remains invested, return of capital targeted to begin once a class has been invested for 36 months, and ongoing participation in profits after all investor classes have been repaid.
- Annual distributions
- The operating company pays the NCE a 9% annual dividend. After NCE operating costs, the remainder is split evenly between the managing partner and the EB-5 investors — the investors’ half is currently estimated at about 2.25% a year on the $800,000 investment.
- Return of capital
- For the first three years, production revenue after the fund’s dividend is reinvested in drilling additional wells. Repayment of a class is targeted to begin once every investor in it has been invested for 36 months; later classes are repaid after earlier ones.
- Profit participation
- Once all investor classes have received their capital back, EB-5 investors receive 35% of all distributed profits from ongoing production.
Repayment timing and distributions are targets, not guarantees, and depend on production performance, operating results and commodity prices. Distributions are subject to available cash flow and the terms of the operating agreement. See the offering documents for complete terms.
Why 36 months
Repayment targeted to begin at 36 months
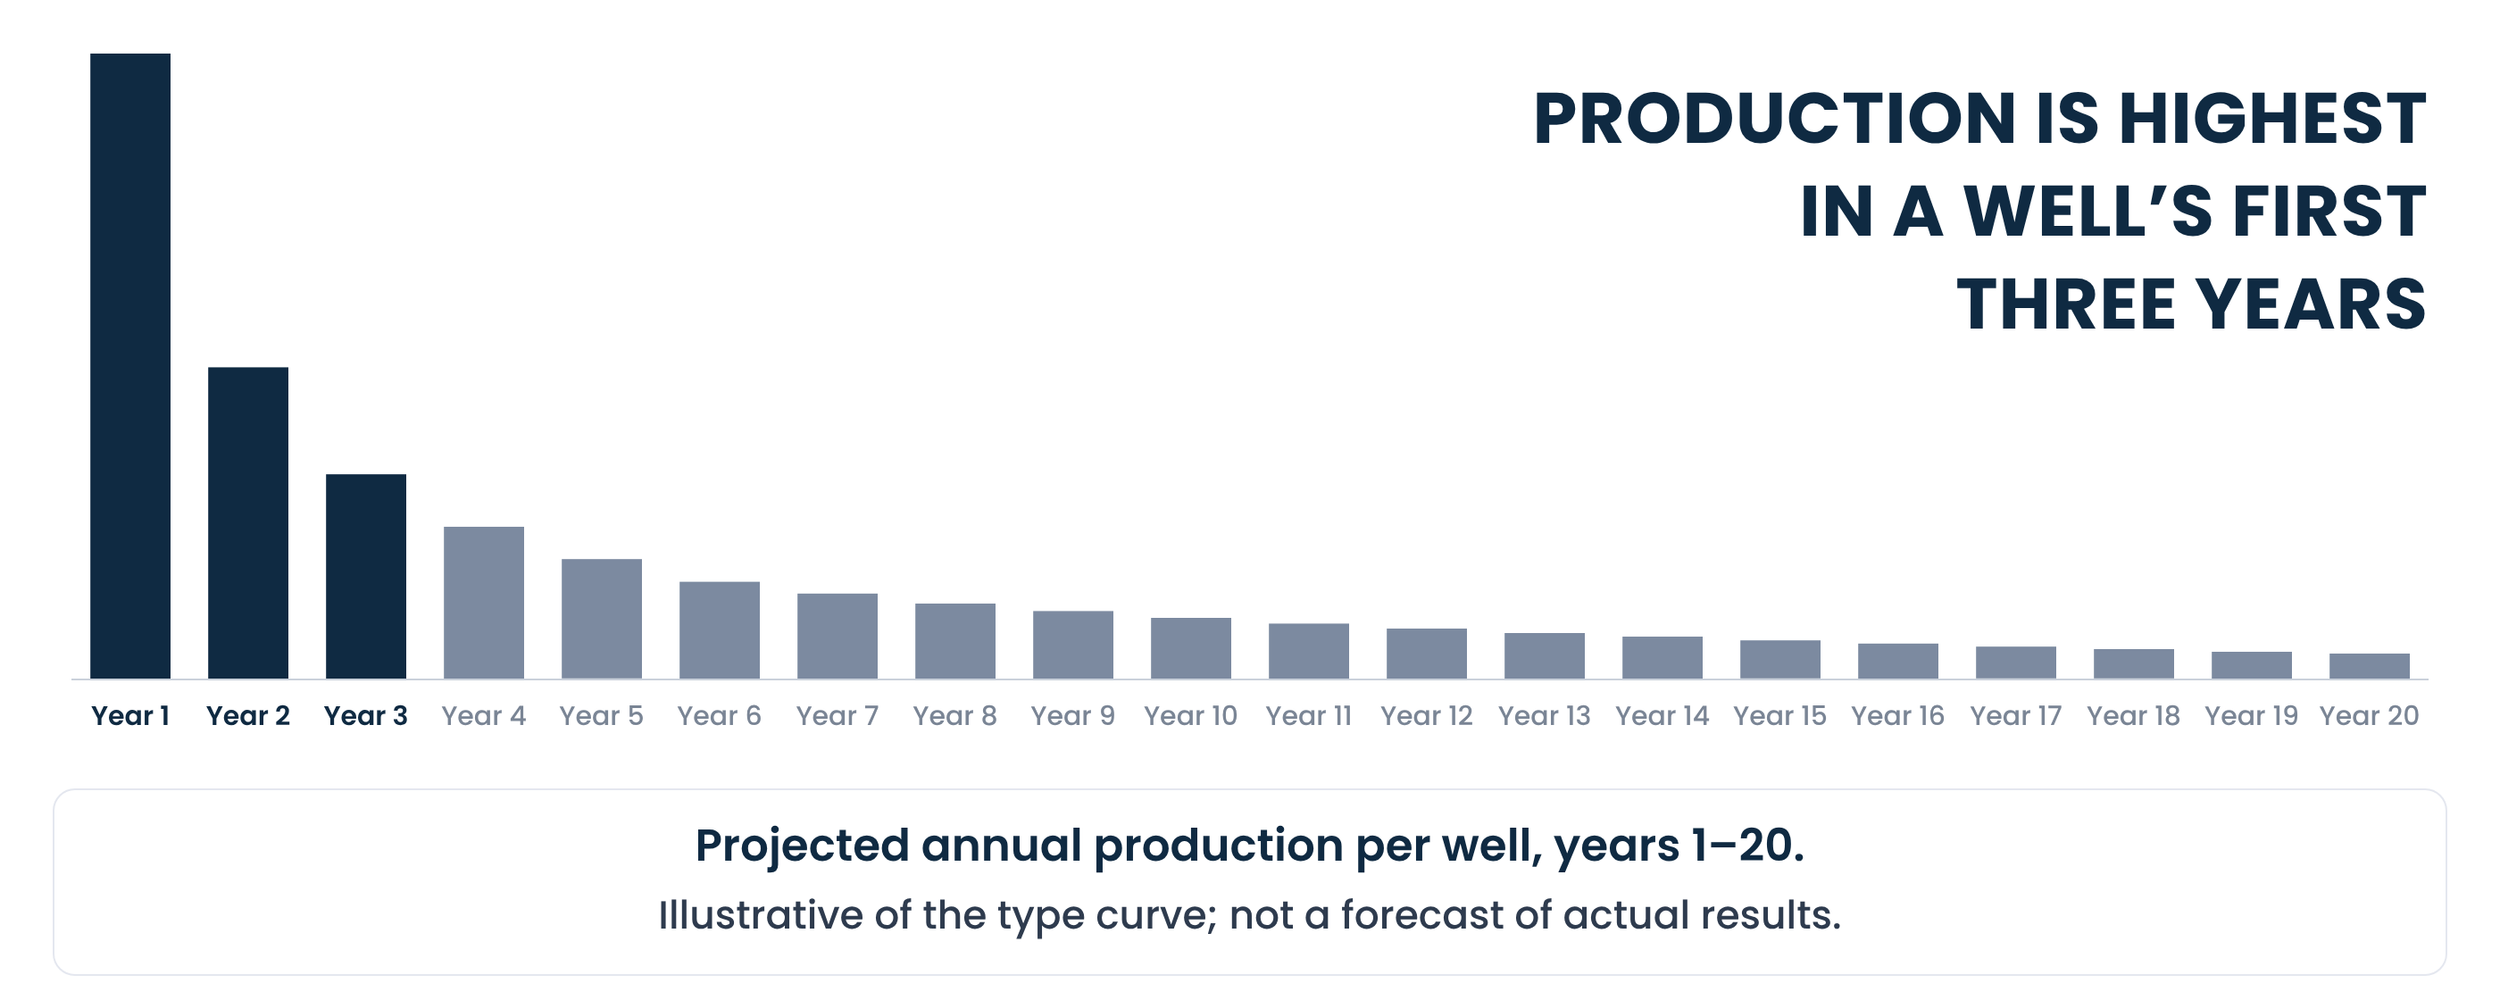
Repayment of each investor class is targeted to begin once every investor in that class has been invested for 36 months. It is designed to come from production cash flow rather than a future refinance or sale. A well typically reaches production about 30 days from the start of work.
Each well costs approximately $4.5 million to complete. At $60/bbl oil and $2.50/Mcf gas (the repayment case), each well is projected to generate approximately $12.6 million in net revenue over its producing life, with just under half of that in the first three years. During those three years, revenue after the fund's dividend is reinvested in drilling additional wells, which builds the production base that repayment draws on.
Repayment and distribution targets are based on production and pricing assumptions. They are targets, not commitments.
In a typical real estate EB-5 loan, repayment depends on the sponsor refinancing or selling the property, on terms set by lending and property markets at that time.
Run the numbers yourself
A well’s economics come down to two things: the price of what it sells, and how much it produces. Production is the harder one — until a well has run long enough to establish a stable decline curve, its best month is the proxy we use. Move any of the three below and the figures update; royalties, taxes and operating costs stay at the project’s assumptions.
This is one well, not your investment.
These figures show the economics of a single well at the project level. They are not what an investor receives. Each well costs about what five to six investors’ capital provides, but investors do not own individual wells: they hold interests in the fund, which shares in every well the project drills. An investor’s return is set by the fund’s terms — an estimated 2.25% a year while capital is outstanding, repayment of capital, and then 35% of all distributed profits to EB-5 investors after all EB-5 investor capital is repaid.
The project’s repayment case assumes oil averages $60.
The same case assumes gas averages $2.50.
The well’s peak month — about 305 barrels a day.
- Operating cash flow, first 7 years
- $6,598,000
- Value of the remaining life at year 7
- $1,610,000
- Less: cost to drill and complete the well
- − $4,500,000
- Total value generated through year 7
- $3,708,000
First three months of production
- Oil
- 23,100 bbl
- Gas
- 107,900 Mcf
- Value at your prices
- $1,209,000
The well’s first three producing months; it is being drilled and completed before that. These are its highest-rate months and the decline is steepest at the start — the third month is already about 18% below the first — so these figures do not annualise.
The repayment case assumes peak oil production of 9,275 barrels per month—about 305 barrels per day. Peak represents a well’s best month, not a sustained production rate, so the model applies the project’s full decline curve over time. Oklahoma state production records for ten newly completed horizontal wells — the same lateral length, completed in the same reservoir, three to seven miles away — show an average peak of about 14,700 barrels per month, approximately 483 barrels per day. The project’s assumption sits below that average. Those results do not guarantee comparable performance from the project wells.
Disclosure
Figures are for one well at 100% working interest, before the fund’s fees and distribution waterfall — they are not an investor return. Where a private firm holds a working interest in a well, the fund’s share of that well’s costs and production is reduced proportionally. For the first three years, production cash flow after the fund’s dividend is reinvested in drilling rather than distributed, and repayment of a class is targeted to begin once every investor in it has been invested for 36 months. A peak month is an early indication of how much a well is likely to produce over its life, and actual production will vary from it. Results are estimates and will differ from actual results. See the offering documents for complete terms.
How investor classes work
Your position is set by when you file — not by how the rest of the raise fills. It determines when your capital comes back, and it is worth understanding before you decide when to act.
First to be repaid.
Repaid after Class A.
And onward, in tens, in the order petitions are filed.
- Classes form in filing order
- Investors are grouped in tens, in the order their I-526E petitions are filed — not by when you enquire or reserve. A class is assigned when funds are wired.
- Jobs are allocated separately
- Qualifying jobs are not allocated by class. Under the PPM they are allocated in the order each investor’s conditional permanent resident status begins — I-485 approval, or first entry on an immigrant visa. The full 72-well program projects 2,232 qualifying jobs against the 1,500 that 150 investors require.
- Repayment follows the same order
- Earlier classes are repaid before later classes, and no profits are distributed to the managing partner or the operators until every class has had its capital returned.
- Repayment begins after 36 months
- Repayment of a class is targeted to begin once every investor in it has been invested for 36 months, from production cash flow. For the first three years, production revenue after the fund’s dividend is reinvested in drilling. Later classes reach 36 months later and are repaid after earlier classes, so a later investor should expect to wait longer. No repayment date is guaranteed for any class.
- What this means in practice
- Waiting is not the cautious choice. Filing later places you behind investors who filed earlier for repayment. Class priority is an ordering, not a guarantee of petition approval or of any particular repayment date.
Two oil prices, two different questions
You will see both figures in our materials. They answer different things, and the difference between them is the point.
The price assumption behind the economic analysis USCIS reviewed, and therefore behind the job-creation model. Job creation is calculated from projected spending and revenue, so the filing has to state a price.
The average price the wells would need to realize for repayment to proceed on target once it begins, starting with the earliest classes. Lower than the filing assumption — the repayment case does not depend on oil holding where the job model put it.
Neither figure is a forecast, and neither is a guarantee. Oil prices move for reasons outside any operator’s control. Sustained prices below the repayment case would extend the timeline; job creation depends on actual spending and revenue, not on the modelled price being achieved.
How the eight wells get funded
Eight wells at roughly $4.5 million each costs more than EB-5 subscriptions alone contribute. Here is how the difference is covered.
- The program is funded progressively
- Wells are drilled as capital becomes available, not all at once. The first eight are financed by EB-5 subscriptions together with private working-interest capital that is being arranged.
- Production revenue is reinvested
- A well typically reaches production about 30 days from the start of work. For the first three years, production revenue after the fund’s dividend is reinvested into drilling subsequent wells rather than distributed — which is what allows a $20 million EB-5 raise to fund an eight-well program.
- Private working-interest capital
- A private firm may purchase a working interest in a specific well at cost and share proportionally in that well’s costs and production, with no promote, carry or fee; the fund keeps the balance of the well. These arrangements are being arranged and are not yet committed. The conditions under which drilling proceeds are set out in the offering documents.
- If subscriptions fall short
- Because the program is phased rather than all-or-nothing, fewer subscriptions means fewer wells drilled on a longer schedule — not a project that stops. The offering documents govern what happens in that case, and you should read them on this point specifically.
Read the offering documents
The private placement memorandum, limited partnership agreement and subscription agreement set out the terms in full and control over anything on this page. They are available to verified investors on request.
Request the documents Schedule a call